Warehousing supports international distribution by giving goods a place to wait, be checked, be sorted and be sent on between a supplier abroad and a customer at home. Without it, every order would travel the full distance from the factory, and every delay at one stage would reach the customer unchanged. With it, goods can be gathered from several suppliers, held near the port or the market, and released in the quantities and at the times that sales require. This guide explains the three places where a warehouse earns its cost on a China-to-India route, how bonded storage works under the Indian Customs Act, how deferring duty can be worked out with a made-up example, and what to check when you choose a warehouse.
For the Chinese end, see our guide to warehousing in Guangzhou for international buyers. For answers to cost questions, see warehousing and distribution FAQs for growing businesses.
Three Places a Warehouse Does Different Work
| Location | Jobs the warehouse does | What it saves you |
|---|---|---|
| Origin, near the supplier | Receives goods from several suppliers, checks quantity and quality, labels, consolidates into one shipment | Several small shipments become one, and faults are found before the ocean voyage |
| Gateway, near the port or an inland depot | Deconsolidates LCL boxes, holds goods under customs control, stores bonded goods, hands over to onward transport | Time between arrival and delivery, and cash tied up in duty |
| Destination, near customers | Stores stock, picks and packs orders, dispatches to customers, handles returns | Delivery time to the customer, and the need to import in small, frequent lots |
CONCOR, the Ministry of Railways enterprise that runs inland depots, lists value-added services of this kind in its disclosure under the Right to Information Act: transit warehousing for import and export cargo, bonded warehousing, consolidation of less-than-container-load cargo and reworking of such cargo at nominated hubs, and air cargo clearance using bonded trucking.
What Warehouses Do for an Importer
- Receive and verify. Count the cartons against the packing list, record damage and note discrepancies in writing before the carrier leaves.
- Deconsolidate and consolidate. LCL cargo has to be separated by consignee on arrival. The National Time Release Study 2025 notes that LCL cargo needs disaggregated clearance because it involves multiple bills of entry, while a full container is processed as a single unit.
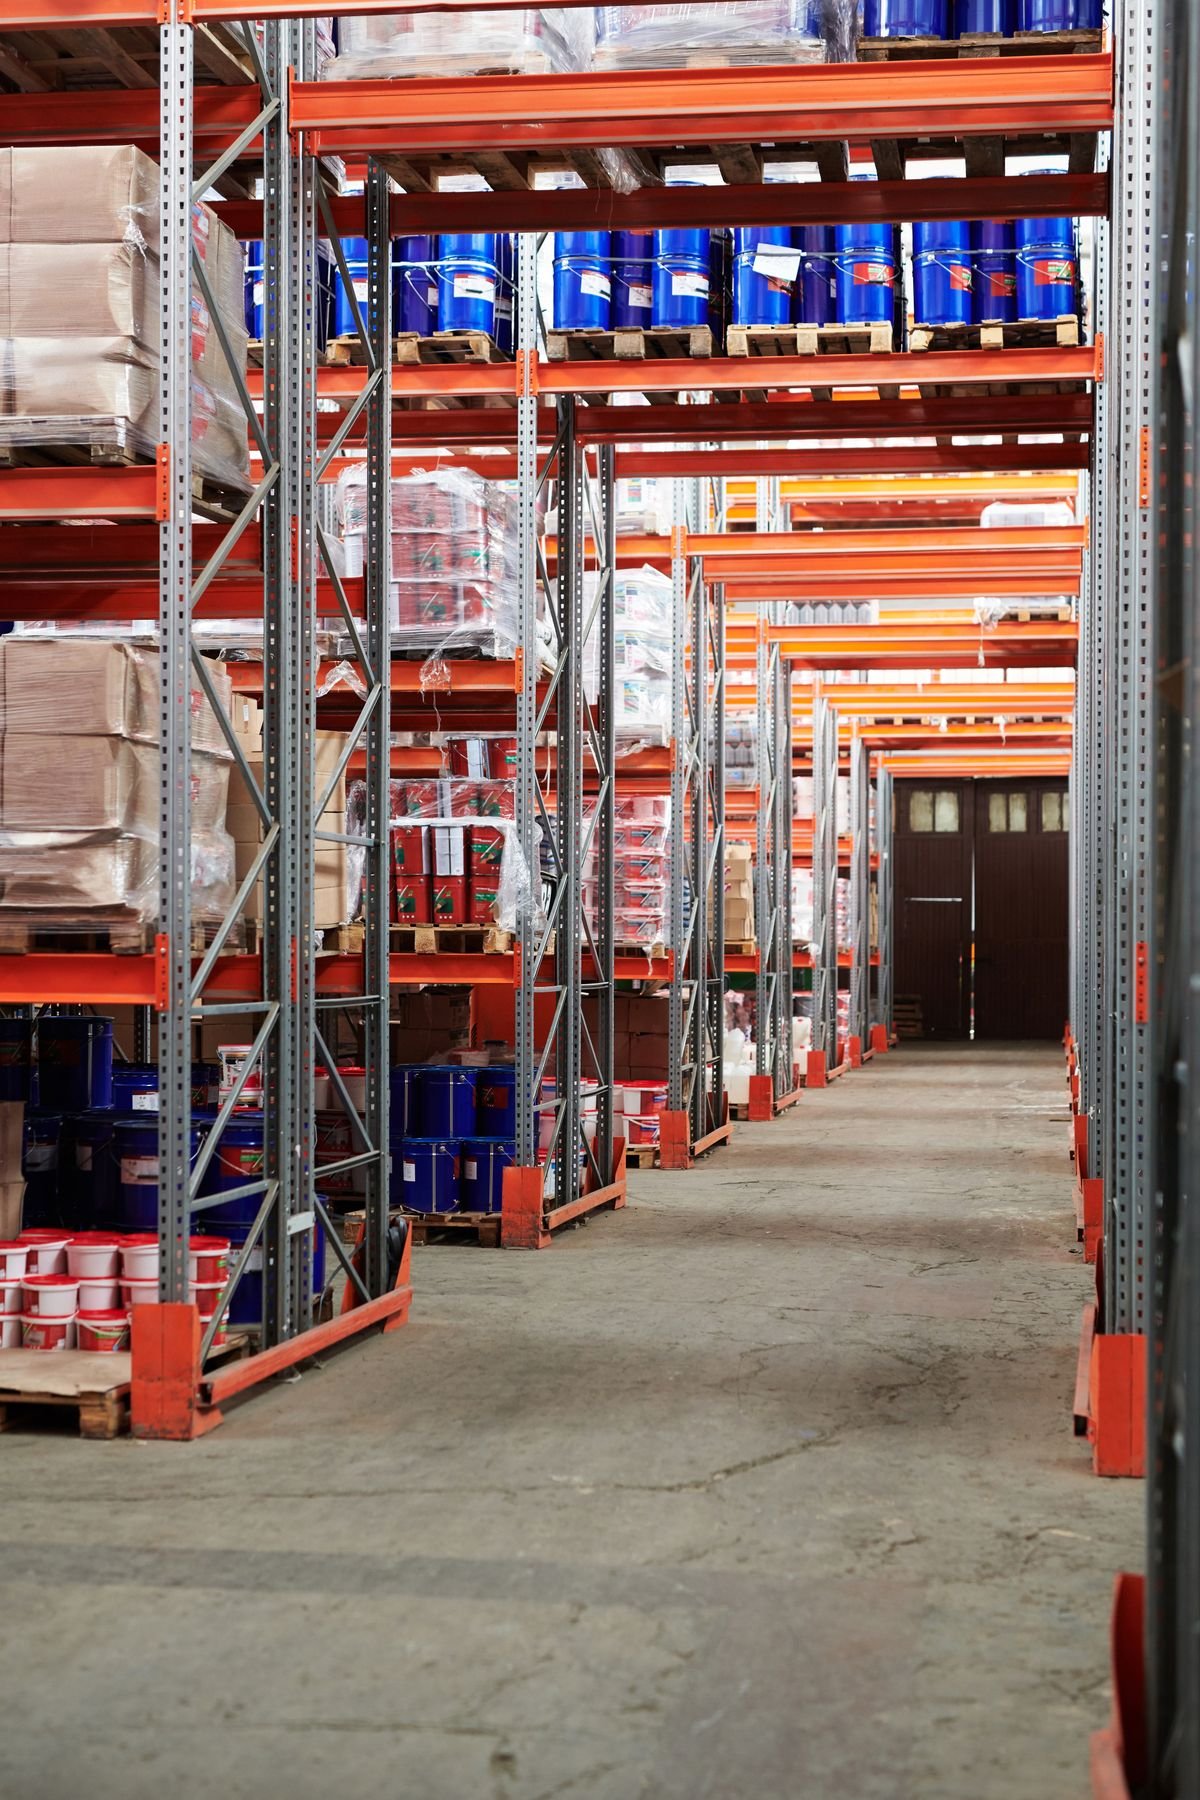
- Store. Hold stock until it is needed, in the right conditions and in a layout that makes each part number easy to find.
- Add value. Relabel, kit, repack or inspect goods so that they leave ready for the customer.
- Pick, pack and dispatch. Turn customer orders into shipments, with cut-off times that match carrier pick-ups.
- Handle returns. Receive, check and route returned goods, which our guide to reverse logistics covers.
The same study measured the average time from a container's arrival at a container freight station to the out-of-charge order, which was about 85 hours across the seaports it assessed, with Mundra at 69 hours 45 minutes, Nhava Sheva at 80 hours 7 minutes, Chennai at 101 hours 30 minutes and Kolkata at 93 hours 22 minutes. In a nearby passage on CFS release times, the study notes that the free storage days container freight stations offer may influence dwell time. Where your goods are handled can therefore affect your lead time.
How Bonded Warehousing Works in India
A bonded warehouse lets an importer store dutiable goods without paying customs duty until the goods are cleared for home consumption or exported. The rules sit in Chapter IX of the Customs Act, 1962, and the main points are below.
| Rule | What the Act says |
|---|---|
| Types | A warehouse is a public warehouse licensed under Section 57, a private warehouse licensed under Section 58 or a special warehouse licensed under Section 58A |
| Bond | The importer executes a bond for three times the duty assessed on the goods, or a general bond that the officer approves, and furnishes prescribed security (Section 59) |
| Permission | Once the bond conditions are met, the proper officer may order the goods removed from the customs station for deposit in a warehouse (Section 60) |
| Period | One year from that order for goods outside the special cases for export-oriented and similar units in Section 61(1)(a) and (b), extendable by the Commissioner by not more than one year at a time |
| Interest | For the same goods, if they stay beyond ninety days from the order, interest is payable on the duty from the end of those ninety days until it is paid, at a rate that the Central Government fixes, unless the Board, in the public interest, waives it in exceptional circumstances or notifies a class of goods for different treatment (Section 61(2)) |
| Rent and charges | Section 63, which used to deal with rent and warehouse charges, was omitted in 2016, so agree these charges with the warehouse operator in writing |
| Export | Warehoused goods can leave for a place outside India without payment of import duty if the export conditions are met (Section 69) |
These provisions are taken from CBIC's consolidated text last updated on 30 March 2022, so ask your customs broker to confirm the current wording before you rely on them.
Para 2.36 of the Foreign Trade Policy 2023 allows any person to import goods other than prohibited items, arms and ammunition, hazardous waste and chemicals, and to warehouse them in bonded warehouses, with customs duty paid at the time of clearance for home consumption. CONCOR says its bonded warehousing lets importers store cargo and take partial deliveries, thereby deferring duty payment. Our guide to bonded warehousing for China imports covers the cash-flow side in more detail.
A Made-Up Duty Deferral Example
An importer brings in goods that will be sold in four equal lots. The duty on each lot is 100 currency units (made up), and the lots are cleared from the bonded warehouse on day 0, day 40, day 80 and day 120. Day 0 is the date of the Section 60 order, and all four lots are deposited on that date.
| Lot | Cleared on day | Duty paid then | Days of deferral |
|---|---|---|---|
| 1 | 0 | 100 | 0 |
| 2 | 40 | 100 | 40 |
| 3 | 80 | 100 | 80 |
| 4 | 120 | 100, plus interest for the days beyond ninety | 120 |
If all four lots were cleared on arrival, the importer would pay 400 at once. Under bonded storage the same 400 is paid in four steps. Multiplying each lot's duty by its days of deferral gives 100 times 40, plus 100 times 80, plus 100 times 120, which is 24,000 unit-days, and dividing by the total duty of 400 shows that the average unit of duty is paid 60 days later. Lot 4 stays beyond ninety days, so interest runs on its duty for the extra thirty days. The bond of three times the duty is a further cost to arrange, so the saving has to be weighed against bond charges, warehouse rent and handling, and the interest. Ask your customs broker to price the arrangement for your goods.
Choosing Where to Hold Stock
- One warehouse near the port or inland depot keeps stock in one place, which suits steady demand and a few customer clusters.
- Regional warehouses shorten the last leg to customers but can hold more stock in total, because each site needs its own buffer. Our guide to hub-and-spoke vs point-to-point networks explains the trade-off.
- Flow-through sites pass goods on within hours, as we explain in what cross-docking is and when to use it.
Inventory policy matters as much as location. See just-in-time vs just-in-case inventory strategies for how much stock each site should hold.
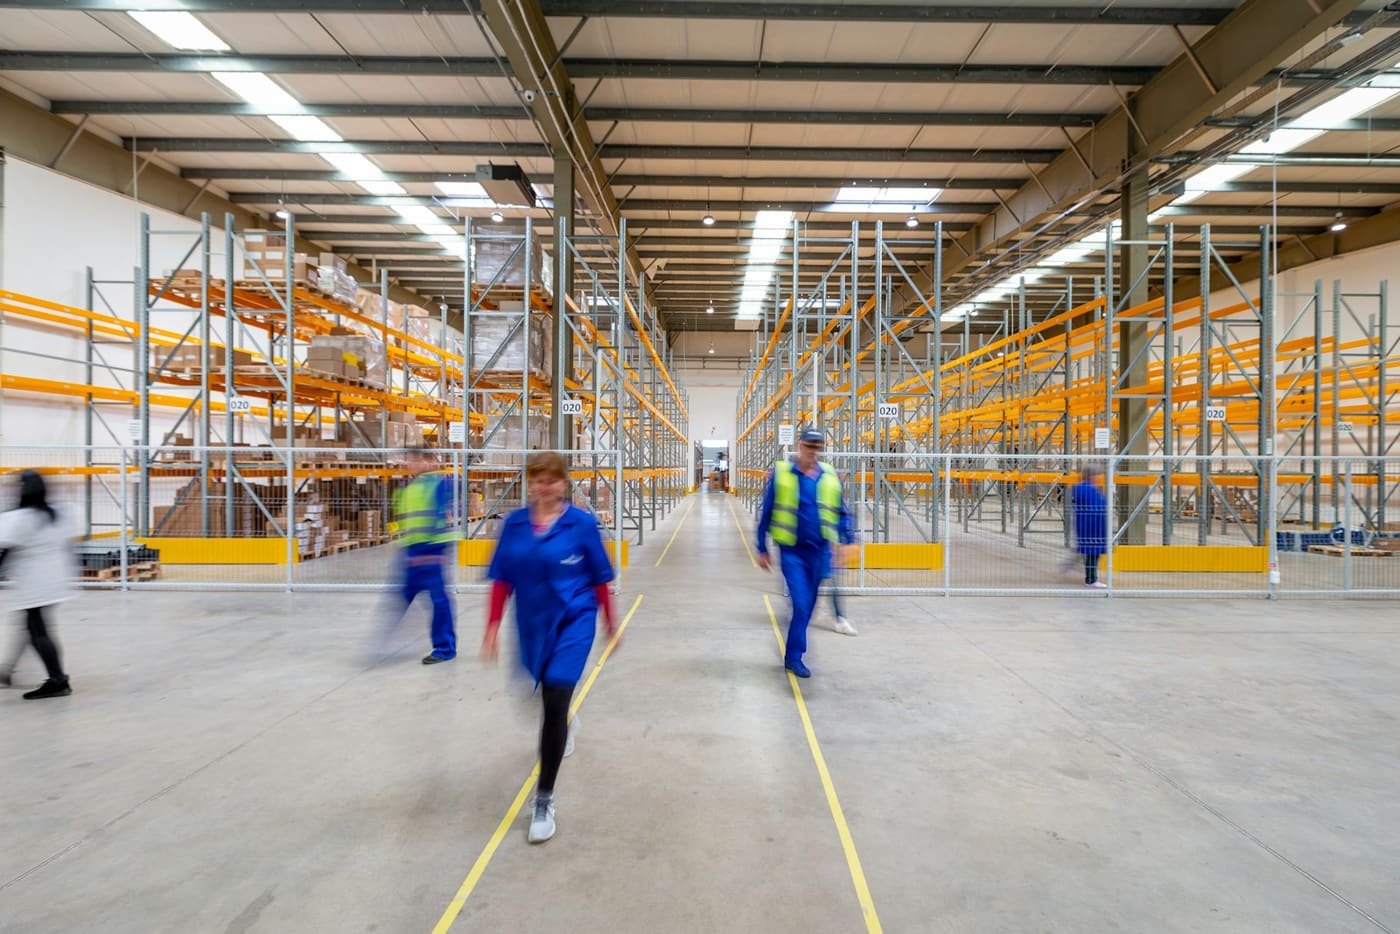
A Warehouse Selection Checklist
- Is the site close to your port, depot or customers, and can trucks reach it easily?
- Does it hold the licences you need, including a customs licence if you want bonded storage?
- Can it receive LCL and FCL cargo, and what are its receiving and release times?
- Which system records stock, and can you see it online?
- Which charges apply for storage, handling in and out, and value-added work?
- How does it protect goods against theft, damage and mix-ups?
- What insurance and liability limits does the operator offer?
- Can the contract flex up and down as your volumes change?
Plan Warehousing With RR Brothers and Logistics
RR Brothers and Logistics supports importers with warehousing and distribution, sea freight to India and customs clearance. Tell us your goods, volumes and customers and we will help you decide where stock should wait and in what form.
Frequently Asked Questions
It lets goods be gathered, checked, sorted and held between supplier and customer, so that shipments can be consolidated at origin, deconsolidated and cleared at the gateway, and dispatched in the right quantities near customers.
A licensed warehouse where dutiable imported goods are stored without paying customs duty until they are cleared. Sections 57, 58 and 58A of the Customs Act cover public, private and special warehouses.
Outside the special cases for export-oriented and similar units, one year from the Section 60 order for deposit in the warehouse, extendable by the Commissioner by not more than one year at a time. Interest on duty runs if goods stay beyond ninety days, unless the Board, in the public interest, waives it or notifies the class of goods for different treatment.
Yes. Section 59 requires a bond for three times the duty assessed, or an approved general bond, plus prescribed security, so the cost of arranging the bond belongs in your comparison.
The National Time Release Study 2025 measured about 85 hours on average from a container's arrival at a container freight station to the out-of-charge order, from 69 hours 45 minutes at Mundra to 101 hours 30 minutes at Chennai. In a nearby passage on CFS release times it notes that free storage days may influence dwell time, and it says LCL cargo needs disaggregated clearance because it involves multiple bills of entry.
Section 69 allows warehoused goods to be exported to a place outside India without payment of import duty if a shipping bill is presented, export duty and penalties are paid and the proper officer orders clearance.
Sources
- CONCOR: Information under Section 4(1)(b) of the Right to Information Act, 2005
- CBIC: National Time Release Study 2025 (released 20 June 2025)
- CBIC: Customs Act, 1962 (Sections 57 to 61 and 69)
- DGFT: Foreign Trade Policy 2023, Chapter 2 (para 2.36)
This article is general information, not legal, tax or customs advice. Rules, rates and procedures change; confirm current requirements with the relevant authority or a licensed customs professional before you ship. Regulatory references were checked against the official sources listed above on 26 October 2026.
Image credits: header photo by CHUTTERSNAP on Unsplash; photo by Adrian Sulyok on Unsplash. Used under the Unsplash License.
Request a Quote